Parental allowance and tax return - how parental allowance is taxed correctly

By Felix Böhme, Dipl.-Finanzwirt (FH), graduate in public finance Updated
Parental allowance is tax-free – and yet many parents face a tax back payment after their parental leave. The reason: parental allowance and maternity benefit raise the tax rate on your other income (progression clause). If the working partner also switches to tax class 3, even less wage tax is withheld during the year – and anyone who has not put money aside gets an expensive surprise with the tax assessment. This article explains what effects parental allowance has on income tax. With our progression calculator you can see in two minutes how much additional tax to expect. In another article, you can read how you can receive a higher parental allowance by applying for parental allowance: Tax class change
The most important facts about parental allowance and income tax
- Anyone who has employment income and receives more than €410 in parental allowance, maternity benefit or other wage replacement benefits in a calendar year must file an income tax return.
- Parental allowance is tax-free, but increases the average tax rate when filing the income tax return.
- Parental allowance is entered in the main form of the income tax return (Hauptvordruck ESt 1 A), in the section „Einkommensersatzleistungen“ (income replacement benefits; 2025 form: line 35).
- The parental allowance office has already notified the tax office of the specific amount of parental allowance you received in the calendar year (electronic data transmission).
The most important tips and advice on parental allowance and tax returns
- The lower the taxable income in a calendar year, the weaker the progression effect.
- Parents who are assessed together, where one earns very well and the other has a high parental allowance, are hit particularly “hard”.
- Set aside money for back taxes if the working parent pays income tax at wage tax bracket 3 during the partner’s parental leave.
- Have your tax liability calculated early to avoid any “bad surprises” – our progression calculator gives you a first estimate.
- The inflow principle applies to progressive income. If parental allowance starts around the turn of the year, plan carefully in which year it is wiser to receive the first (back) payment from the parental allowance.
- It can pay off to move parental allowance into a year in which you have hardly any taxable income – for example by first receiving ElterngeldPlus in the year of birth and applying retroactively for basic parental allowance after the turn of the year. Merely spreading parental allowance over two years, on the other hand, usually saves nothing. Our progression calculator shows whether it pays off for you.
Is parental allowance subject to income tax?
No, it is even explicitly tax-free, see § 3 No. 67 lit. b) Income Tax Act. This means that the parental allowance is transferred 1:1 by the parental allowance office without tax deductions. However: According to § 32b para. 1 p. 1 lit. j) Income Tax Act, the parental allowance is subject to the so-called progression proviso. The progression proviso refers to a special calculation process in the income tax calculation, in which tax-free benefits, indirectly increase the tax rate on taxable income.
The best way to explain this is with a simple example:
Your taxable income in 2026 is EUR 50,000 (individual assessment). According to the tax scale, income tax is EUR 10,548, an average tax rate of about 21.1%. Now the tax office checks whether you received progression benefits (parental allowance, maternity benefit, sickness benefit, unemployment benefit I, etc.) in this year. Let's assume you received EUR 10,000 parental allowance. Your 'fictitious' taxable income is now EUR 60,000 and the average tax rate would be about 23.7%. This higher rate is applied to your EUR 50,000: income tax rises by about EUR 1,312 to EUR 11,860 (simplified example without solidarity surcharge and church tax). The parental allowance itself remains tax-free – it only raises the tax rate on your other income.
You can work out your own figures with our progression calculator.
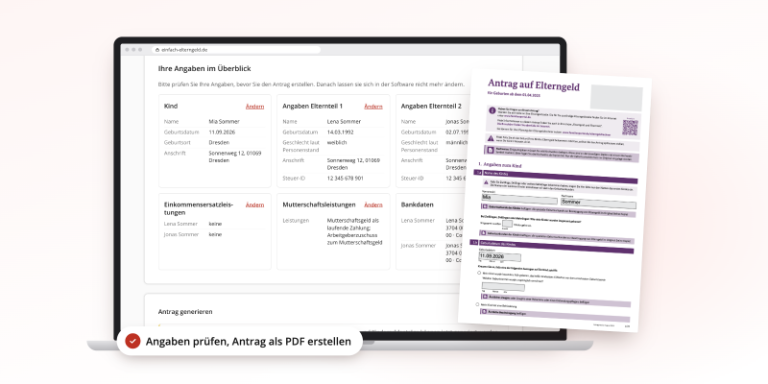
Progression calculator: how much tax does parental allowance cost you?
How much tax do maternity benefit and parental allowance cost you? Enter your salary and the due date – the calculator shows the expected additional tax for each year concerned, explains in plain words how it comes about and runs two comparisons: Is it worth taking ElterngeldPlus first and switching to basic parental allowance later? And for married couples, is a joint or a separate tax return cheaper? It works for parents who file their tax return on their own and for couples filing jointly. Your details stay in your browser.
How the calculator works
The calculator estimates your taxable income for each calendar year from your salary (salary minus the employee lump sum, statutory social security contributions and the lump sum for special expenses) and compares income tax without and with maternity benefit, employer top-up and parental allowance (progression clause, Section 32b EStG). The part of the employee lump sum not used up by salary is deducted from the benefits. Parental allowance counts in the year it is paid; payment is assumed at the end of each month of life. Solidarity surcharge and church tax are included; child allowances, childcare costs, private health insurance and other deductions are not. The result is a guide; your tax assessment is binding. Your details stay in your browser and are not stored.
Comparison 1: ElterngeldPlus first, then basic parental allowance?
For tax purposes, parental allowance counts in the year in which it reaches your account. You can move part of it into the next year like this:
- For the months of life in the year of birth, you first apply for ElterngeldPlus. If you do not work after the birth, this is exactly half of the basic parental allowance.
- After 1 January you change your application: for the months in which you received ElterngeldPlus, you apply retroactively for basic parental allowance. The law expressly allows this – even for months more than three months back (Section 7 (2) BEEG).
- The parental allowance office pays the second half – in the new year. Only there does it count for tax.
In total you receive exactly as much parental allowance as with basic parental allowance from the start. The rule of thumb: it only pays off if you have (almost) no taxable income in the following year. Where there is no income, a higher tax rate cannot cost anything. Merely spreading parental allowance over two years saves nothing – it often even costs a little more, because with smaller incomes the tax rate rises particularly quickly with every additional euro.
Example 1 – it pays off: Lena files her tax return on her own. Her child is born on 15 June 2026. She earns €4,000 gross (€2,600 net) and stays on parental leave without salary until the end of 2027 after the parental allowance. With basic parental allowance from the start, she pays about €1,480 more tax for 2026. With “ElterngeldPlus first”, €3,380 of parental allowance moves into 2027 – Lena has no taxable income there, so the money costs no tax. Saving: about €235. The price: she is missing the €3,380 from September until the back payment in the new year.
Example 2 – it does not pay off: Sarah has the same salary, her child is born on 15 March 2026, and from mid-March 2027 she works full-time again. In 2026 she only earned in January; her taxable income is about €2,000, and the parental allowance hardly has any effect there (about €195). In 2027 she earns again (about €29,600 taxable) – every euro moved there raises the tax rate on that income. With the strategy she pays about €530 more.
Example 3 – hardly ever for couples: Anna and Tom file a joint tax return. Anna (€4,000 gross) stays at home after the parental allowance, Tom earns €5,000 gross. Thanks to Tom’s salary, they have a similarly high joint income in both years (about €49,000 and €47,000). Moving the money costs them about €160 more. As long as the partner keeps earning, the strategy hardly ever helps with a joint tax return.
Please note: the change must reach the parental allowance office before the end of your benefit period. In the year of birth you only have half of the parental allowance at first – plan for this financially. If you work part-time while receiving parental allowance, ElterngeldPlus is usually more than half; then the calculation looks different. Every month you change to basic parental allowance counts as a full basic month. Please check the months in your change application carefully; the parental allowance office decides on the change.
Comparison 2: Joint or separate tax return?
Married couples can choose every year whether to file jointly (joint assessment) or separately (individual assessment). Filing jointly is usually cheaper: the income is split (income splitting), so the partner with the higher salary pays a lower tax rate. With a joint return, however, parental allowance and maternity benefit also raise the tax rate on the partner’s salary. With separate returns they only affect the parent who received them.
Example 4: Julia (€6,000 gross, €1,800 parental allowance) and Ben (€2,500 gross) are married; their child is born on 15 March 2026. In 2026 Julia receives a lot of maternity benefit and parental allowance but only one month’s salary. Filing jointly, the parental allowance would also raise the tax on Ben’s salary – separately they save about €350 for 2026. In 2027 Julia no longer has any salary; now income splitting brings a lot, and filing jointly is about €2,000 cheaper. So the two are best off filing separately for 2026 and jointly for 2027.
The calculator above runs both comparisons for your own figures. When filing, you can have both types of assessment calculated in your tax software or by an income tax assistance association before you submit. The examples are rounded and assume employees with statutory health insurance and no church tax.
How is parental allowance taxed? Entering parental allowance in the income tax return.
Parental allowance, like other income replacement benefits subject to progression (ALG I, maternity leave payment, sickness benefit, short-time allowance, etc.), is entered in the main form of the tax return in the section „Einkommensersatzleistungen“ (income replacement benefits; 2025 form: line 35), separately for each person. Do not enter your employer’s top-up to maternity benefit there: it is shown on your wage tax certificate and belongs in Anlage N.
Extract from the official main form ESt 1 A 2025:
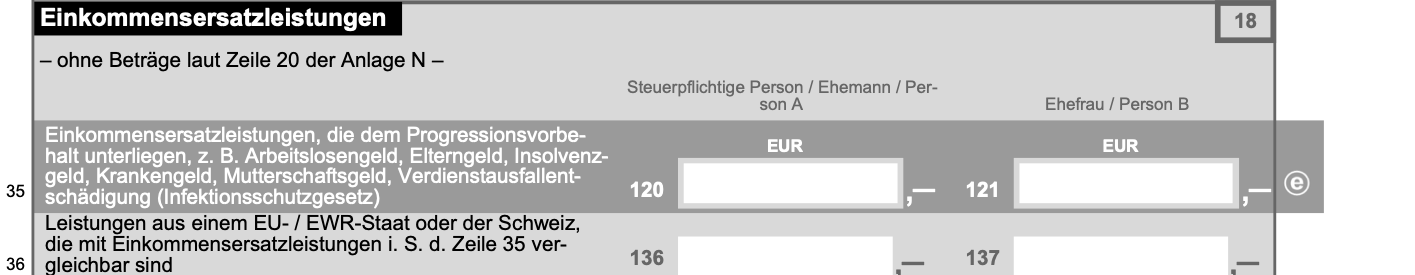
The parental allowance office has already transmitted the amount of your parental allowance to the tax office electronically. If you participate in the electronic data retrieval procedure, you can automatically transfer the parental allowance to the correct line.
Tip: employee lump sum
Before the tax office calculates the tax rate, it deducts the employee lump sum (€1,230) from parental allowance and maternity benefit – but only the part that has not already been used up against your salary (Section 32b (2) EStG). You therefore benefit mainly in a year in which you had no or only little salary, for example the year after the birth. If you worked in the same year, the lump sum has usually already been used up against your salary. This also applies if your actual work-related expenses exceeded €1,230 (Federal Fiscal Court, ruling of 25.09.2014, III R 61/12; the Federal Constitutional Court did not accept a constitutional complaint against it for decision). An objection on this ground alone is therefore no longer useful.
How do I avoid an additional payment for income tax?
Income tax is an annual tax. This means that the tax office checks with your tax return how much income tax you have to pay for the past calendar year. Whether you have to pay tax in arrears or receive a refund depends on how much you have paid in advance. There are different variants of income tax prepayments. The best known are probably:
- the payroll taxes (employees, civil servants, etc.),
- the quarterly advance income tax payments (self-employed, tradesmen, landlords, etc.) and
- the capital gains taxes.
If you are assessed alone (single, permanently separated, etc.), there is generally only an increased risk of an additional payment if you have above-average taxable income while receiving parental allowance (for example, due to rental income or similar).
Couples assessed together should examine the situation more closely. The greatest risk of an additional payment exists if both parents earned above-average wages before the birth and after the birth one parent receives the maximum amount of parental allowance while the other partner changes to tax class 3 with a continued high income or – if self-employed – has the advance income tax payments reduced.
FAQ
-
Where do I enter parental allowance on my tax return?
-
How much tax do I have to pay in arrears because of parental allowance?
-
When does parental allowance have to be taxed?
-
Is parental allowance taxable?
-
Do I have to file an income tax return because of the parental allowance?
You might also be interested in